Financial due diligence is the check a buyer or investor makes, through their accountants, that the profit, cash, assets and liabilities you have described are real and will continue after the deal. They ask for three years of accounts, recent management accounts, aged debtor and creditor lists, a calculation of normalised profit, your tax history, key contracts and payroll records. Start preparing two to three years before you expect to sell or raise money, so that the years the buyer looks at are the years you have tidied.
What a buyer's accountants ask for
The buyer's accountants send a request list early in the process, and you or your advisers load the documents into a data room, an online folder that the buyer's team can read. A request list for an owner-managed business covers:
- Annual accounts for the last three years, and the Corporation Tax returns that go with them
- Management accounts for each month of the last two or three years and the current year to date
- The budget and forecast for the current year and the next
- Aged debtor and creditor lists at each year end and at the latest month end
- Sales by customer, product and month, and gross margin on the same basis
- Bank statements and reconciliations, and details of every loan, overdraft, lease and hire purchase agreement
- VAT, PAYE and Corporation Tax returns, payments and correspondence with HMRC
- Payroll records: every employee's pay, contract, start date, pension and any bonus or commission scheme
- Contracts with the largest customers and suppliers, property leases and any agreements with the owners
- The director's loan account and every transaction between the company and its owners
Each question the buyer's accountants cannot answer from the documents becomes a question to you, and each answer that changes the profit or the debt can change the price.
Quality of earnings
A quality of earnings review tests whether the profit in the accounts is a fair guide to the profit the buyer will earn. The buyer's accountants look at how much of the sales repeat every year from contracts or regular customers, and how much came from one-off work. They look at how much of the sales come from the largest customers, how the gross margin has moved, and how much of each year's profit turned into cash in the bank. They also check that sales and costs fall in the right year, so that a strong final year does not include sales invoiced early or costs held back.
Monthly management accounts kept on the same basis for three years answer most of these questions directly. The guide to gross margin covers how to calculate it by product and customer, which is the breakdown buyers ask for.
Normalised profit and add-backs
Normalised profit is the profit the business would make under its new owner, with one-off items and costs that belong to the current owner taken out. The buyer values the business on this figure, often as a multiple of normalised EBITDA, so each adjustment moves the price by the same multiple. Add-backs increase the profit and deductions reduce it, and the buyer's accountants test each one against evidence.
Normalised profit for the last year
| Operating profit in the accounts | £380,000 |
| Add: legal costs of a settled dispute with a former supplier | £25,000 |
| Add: the owner's personal car and costs paid by the company | £12,000 |
| Add: rent above the market rate, paid to the owner's property company | £15,000 |
| Less: cost of a managing director above the owner's current salary | -£45,000 |
| Less: one-off grant income | -£10,000 |
| Normalised profit | £377,000 |
An example on invented round numbers.
In the example the owner pays themselves a low salary and takes the rest as dividends, so a buyer who has to employ a managing director at a market salary deducts the difference. The rent add-back holds only if the lease is reset to the market rate as part of the sale, and the buyer will ask for a valuation to support it. An add-back with no evidence behind it, or a cost described as one-off that appears every year, is struck out, and each one struck out reduces the price.
Debtors, creditors and working capital
The buyer's accountants read the aged debtor list for slow payers and debts that will not be collected, and the aged creditor list for suppliers paid late to hold cash in the bank at the year end. A sale agreement can set a normal level of working capital the business must hand over on completion, measured from the monthly balance sheets over the past year, with the price adjusted up or down for the difference. The guide to working capital explains how it is measured, and the guide to reducing debtor days covers how to bring customer debts down before a sale.
Tax compliance history
The buyer inherits the company's tax history, including any tax underpaid in earlier years. A limited company must keep its records for six years from the end of the last financial year they relate to, and longer in some cases, such as when HMRC is carrying out a compliance check (GOV.UK). The buyer's accountants ask for the returns and payments for VAT, PAYE and Corporation Tax over that period, any penalties or interest charged, and any enquiry or dispute with HMRC.
The sale agreement then asks you to confirm that the tax affairs are in order, and to repay the buyer for tax relating to the years before completion. Clear any late returns, settle any open enquiry and check how benefits, expenses and payments to directors have been treated before the buyer looks.
Record keeping: GOV.UK, Running a limited company, company and accounting records.
Contracts and payroll
Read your largest customer and supplier contracts for clauses that let the other side end the contract if the company changes owner, and for contracts that run out soon after the expected sale date. Check that property leases are signed and current. Every employee should have a written contract, and payroll should match the contracts, with pension contributions paid on time and holiday, overtime and bonuses calculated correctly. Any amount the company owes the directors, or the directors owe the company, will be settled as part of the deal, so keep the director's loan account up to date and agree its balance.
When to start preparing
The buyer reads the last three years of accounts, so changes made two to three years before a sale show in every year they examine. In that time you can:
- Produce monthly management accounts on the same basis every month
- Stop paying personal costs through the company, so fewer add-backs need evidence
- Put rent and directors' pay at market rates, or document why they differ
- Settle disputes and clear any late tax returns or payments
- Put written contracts in place with customers, suppliers and staff
- Build a forecast for the next two years that the results then meet
The guide to business exit planning covers the wider preparation for a sale, including tax and the owner's role.
Preparing for a sale or investment with Buzz
The Buzz Finance Director service costs £2,000 + VAT a month and includes a one-page plan, a 12-month cash flow forecast, a KPI dashboard, a quarterly board meeting and the finance team's day-to-day work. The pages on a finance director before selling a business and a finance director before raising investment set out the preparation work for each.
Questions
What is financial due diligence?
Financial due diligence is the check a buyer or investor makes, through their accountants, that a business's profit, cash, assets and liabilities are as described. It covers the last three years of accounts, the management accounts, the quality of the profit, working capital, debt, tax history, payroll and the main contracts. The findings can change the price, the terms of the sale agreement or whether the buyer goes ahead. The buyer's accountants send a request list early in the process, and you load the documents into a data room. Each question they cannot answer from the documents becomes a question to you. Start preparing two to three years before you expect to sell or raise money, so the years the buyer examines are the years you have tidied. The guide to business exit planning covers the wider preparation for a sale.
What are add-backs in a business sale?
Add-backs are costs added back to the profit in the accounts to show the profit the business would make under a new owner. They include one-off costs such as legal fees on a settled dispute, and costs that belong to the current owner, such as a personal car paid for by the company. The buyer's accountants test each add-back against evidence and strike out any they cannot verify. Deductions work the other way: a buyer who has to employ a managing director at a market salary deducts the difference from the owner's low salary. In an example, £380,000 of operating profit with £52,000 of add-backs and £55,000 of deductions gives normalised profit of £377,000. Paying fewer personal costs through the company in the years before a sale means fewer add-backs need evidence.
What is normalised EBITDA?
Normalised EBITDA is earnings before interest, tax, depreciation and amortisation, adjusted to take out one-off items and costs that will not continue after a sale. Add-backs increase it, and deductions such as the market cost of replacing an owner who takes a low salary reduce it. Buyers value an owner-managed business on this figure, so each adjustment moves the price by the multiple the buyer applies. In the example, rent above the market rate paid to the owner's property company is added back only if the lease is reset to the market rate as part of the sale, and the buyer will ask for a valuation to support it. A cost described as one-off that appears every year is struck out, and each one struck out reduces the price. The page on a finance director before selling a business covers the preparation.
How far back does financial due diligence go?
Financial due diligence looks at the last three years of accounts and monthly management accounts, and the current year to date. Tax checks can go further back, because a limited company must keep its records for six years from the end of the last financial year they relate to (GOV.UK), and the buyer takes on any tax underpaid in those years. The forecast for the current and next year is read alongside the history. The buyer's accountants ask for VAT, PAYE and Corporation Tax returns and payments over that period, any penalties or interest and any enquiry with HMRC. Clear any late returns and settle any open enquiry before the buyer looks.
What is a data room in due diligence?
A data room is a secure online folder where the seller places the documents the buyer's advisers have asked for. The buyer's accountants and lawyers read the documents there and raise questions, and the seller's answers are recorded alongside them. Organising the folders to follow the buyer's request list, with each document named clearly, shortens the time the review takes. The request list for an owner-managed business covers three years of annual accounts and tax returns, monthly management accounts, aged debtor and creditor lists, sales by customer and product, bank and loan details, VAT and PAYE records, payroll, the main contracts and the director's loan account. Keep each answer with the document it relates to, so each point is found and checked once.
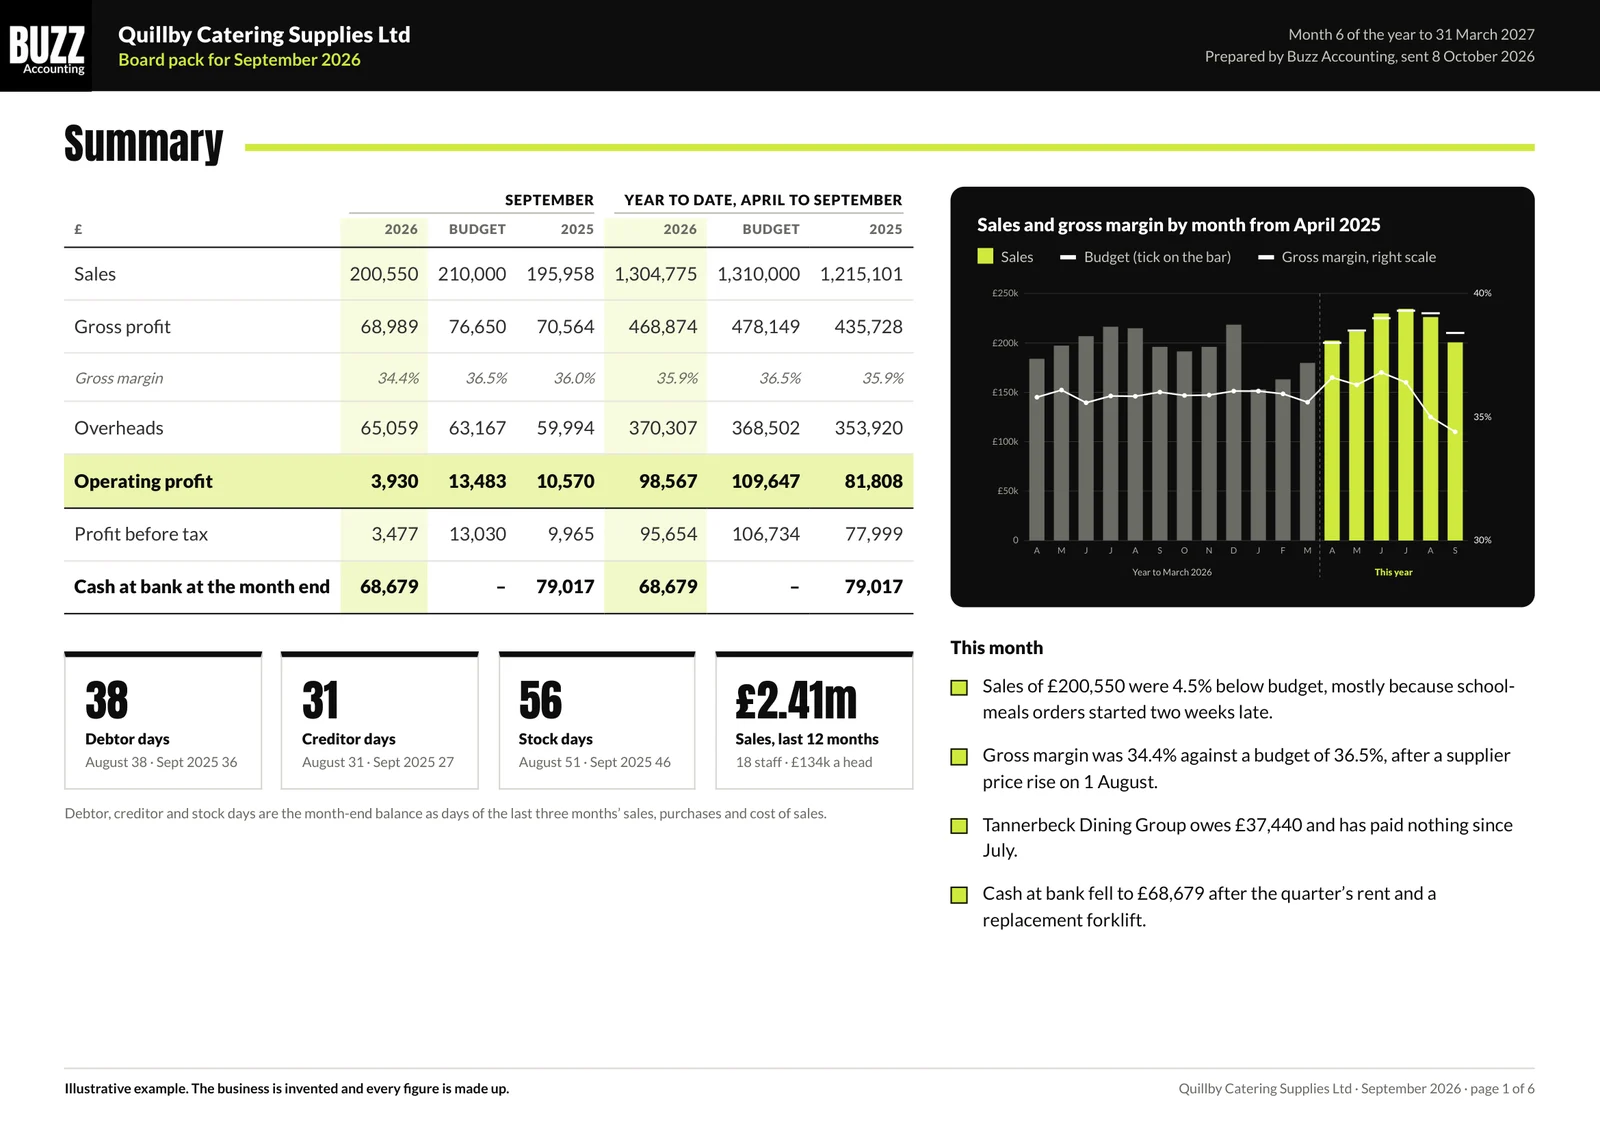
Sample monthly board pack
Six pages for one month at an invented catering wholesaler with 18 staff, prepared the way the finance team prepares one for a client.
- 1Summary
- 2Profit and loss
- 3Balance sheet
- 4Cash
- 5Customers and suppliers
- 6Commentary
More guides
What a bank wants to see in a business plan
What a lender reads in a business plan: the amount and purpose, ability to repay, forecasts, assumptions, security, guarantees and the people running it.
Bank loan covenants explained
The financial covenants in a bank loan, how interest cover, debt service cover and net debt to EBITDA are worked out, and how to see a breach coming.
Cash flow forecast for a lender
The forecast a bank or lender asks for, and what they check in it.
Business exit planning
Getting a business ready to sell or hand on.
Finance director before selling a business
Getting the figures, forecast and records ready for a buyer.
The 13-week cash flow forecast
How to build a 13-week cash flow forecast, update it every Monday and act on it, with payroll, PAYE, VAT and Corporation Tax in the right weeks.
Month-end close for a small business
How to close the books by working day 10: the reconciliations, accruals and prepayments, the review, and what the management accounts should show.
Debtor control and getting paid faster
Payment terms, invoicing, a chase sequence by day, debtor days, and statutory late payment interest and compensation at the rates on GOV.UK today.
The monthly KPI pack and board pack
The 8 to 12 numbers an owner-managed business should see every month, how to read them, and what a monthly board pack contains, with a worked example.
13-week cash flow forecast template
A free Excel template for the next 13 weeks of receipts, payments and bank balance.
Sample board pack
A six-page monthly board pack to download.
Cash flow forecasting
How to build a 12-month forecast and keep it up to date.
How to read a cash flow forecast
What each line means and where a tight month shows up.
Why a profitable business runs out of cash
Profit is counted when you invoice and cash moves when you are paid. Where the difference goes, how much cash you need, and ways to release it.
How to reduce debtor days
How to work out debtor days, the steps that bring them down, from payment terms to a weekly chasing routine, and the cash a lower figure releases.
Charging interest on late payments
Statutory interest at 8% above base rate, the fixed sums of £40, £70 and £100, when the late payment law applies, how to claim and how to word your terms.
Setting aside money for VAT, PAYE and Corporation Tax
When VAT, PAYE and Corporation Tax are due, how to work out what to move to a tax account each month, and a worked example for a limited company.
CIS deductions and a builder's cash flow
How CIS deductions of 20%, 30% or nothing reduce what a subcontractor banks on each invoice, HMRC deadlines, and gross payment status.
Outsourced credit control and how it works
What an outsourced credit controller does each week, how it runs in your Xero, what it costs against employing one, and the cash it releases.
Cash flow forecasting in Xero
What Xero's short-term cash flow projection shows, what it leaves out, and how to keep a 13-week or 12-month forecast alongside Xero.
Management accounts explained
The contents of a monthly management pack, and how to read it.
KPIs to check every month in a small business
The KPIs an owner-managed business checks each month, how to set targets, leading and lagging measures, and a worked monthly KPI sheet.
Sample board pack
A six-page monthly board pack to download.
Gross margin explained
What gross margin is, how it differs from mark-up, how to calculate it, what moves it and why to check it monthly, with a worked example of the confusion.
Working capital explained
What working capital is, how to calculate it from a balance sheet, the working capital cycle in days, why growth uses cash, and a worked example.
Budget against actual variances explained
How to compare each month's results with the budget, tell favourable from adverse variances, split price from volume and decide which ones to act on.
What management accounts cost and include
Management accounts from £375 a month quarterly or £499 monthly + VAT: what a monthly set contains, what the owner provides and when it should arrive.
Management accounts for a construction company
Management accounts for builders and contractors: work in progress, retentions, CIS deductions, the VAT reverse charge and margin by contract.
Setting up monthly management reports in Xero
How to set up monthly management reports in Xero: the ledger work first, then the Management Report pack, budget variance, tracking and commentary.
How to price for profit
What a price change does to profit, worked through.
Turnover up, profit down
Why sales can rise while profit falls, and where to look.
How to set an annual budget for your business
Six steps to next year's budget, a month-by-month worked example, seasonality, wage rises from April 2026, and reforecasting during the year.
Break-even point explained
How to work out break-even in sales and in units from fixed costs, variable costs and contribution margin, with a worked example and the margin of safety.
What a price rise does to profit
How a small price rise flows straight to profit, how many customers you could lose and still be better off, and how much more you must sell after a discount.
Job costing for small businesses
How to cost each job with materials, labour at a loaded hourly rate, subcontractors and overheads, compare quoted with actual, and value work in progress.
What does a part-time finance director do?
What a part-time or fractional finance director does, the first three months, how it differs from a financial controller, and what one costs.
Finance manager or financial controller?
What a finance manager does, what a financial controller adds, the month-end close, deadlines, how to choose, and what each costs to employ or outsource.
Month-end close checklist
The steps to close the books within five working days: bank, ledgers, accruals, prepayments, payroll, VAT, stock, fixed assets and a final review.
In-house or outsourced bookkeeper?
What employing a bookkeeper costs once National Insurance, pension and holiday cover are added, what an outsourced service covers, and how to switch.
How to run a monthly board meeting
Who attends a board meeting in an owner-managed company, what goes in the board pack, a standard agenda, the decisions and actions log, and the minutes.
Replacing a bookkeeper who has left
Keeping payroll, VAT and the books running when your bookkeeper goes.
The cost of employing a financial controller
What a finance manager, financial controller and finance director cost to employ in 2026 to 2027, with National Insurance and pension, against Buzz fees.
Talk to us
Tell us about the business and what is taking up your week, or book 30 minutes with Peter. He will come back within 48 hours with the level that fits and a fixed monthly fee.
Book a callOr call
07476 989568Accreditations and partners