The month-end close is the set of checks and adjustments that turn a month of bookkeeping into figures you can rely on. For a small business it can be done within five working days of the month end: reconcile the bank, check the sales and purchase ledgers, post accruals, prepayments, payroll and depreciation, reconcile VAT and stock, and review the result before it goes into the management accounts.
Bank reconciliation
By the end of the first working day, every bank account, credit card, loan and payment app (such as a card terminal or online payment provider) should be reconciled to its statement balance on the last day of the month. Every transaction is matched to an invoice, a bill or a coded entry, and nothing is left in suspense. A reconciled bank is the base for every other step.
- Each bank and card account reconciled to the statement balance
- Card terminal and payment provider balances agreed, with fees posted
- Loan balances agreed to the lender's statement, with interest posted
- Transfers between accounts matched on both sides
Sales and purchase ledgers
On the second day, check that every sale made in the month has been invoiced and every supplier bill received has been posted.
- All work done or goods delivered in the month invoiced
- Aged debtors list reviewed, with old or disputed balances followed up
- Supplier statements agreed to the purchase ledger for your main suppliers
- Aged creditors list reviewed for bills that are overdue or posted twice
- Credit notes posted against the invoices they relate to
The aged debtors list also feeds credit control. The guide on how to reduce debtor days covers the follow-up.
Accruals and prepayments
Accruals bring in costs that belong to the month and have not yet been billed, such as energy, telephone, a subcontractor's work or the accountant's fee. Prepayments take out the part of a bill that belongs to later months, such as an annual insurance premium or software paid a year in advance. Both reverse at the start of the next month.
Adjustments at the month end
| Profit from the bookkeeping before adjustments | £18,000 |
| Electricity used in the month, bill not yet received | −£1,200 |
| Annual insurance of £6,000 paid this month: 11 months carried forward | +£5,500 |
| Depreciation on a £30,000 van over five years | −£500 |
| Increase in work in progress on unfinished jobs | +£2,000 |
| Profit for the month | £23,800 |
An example on invented round numbers.
Without the adjustments, the month would show £18,000 of profit. The insurance would make this month look poor and the next eleven look better than they were.
Payroll journal
Post the payroll journal from the payroll report: gross pay, employer National Insurance and pension as costs, with net pay, PAYE and National Insurance owed to HMRC, and pension contributions owed to the provider as liabilities. Each Full Payment Submission has to reach HMRC on or before the day your employees are paid (GOV.UK). Agree the PAYE and pension control accounts to what is due, and check last month's balances were paid in full.
VAT control account
Reconcile the VAT control account so its balance equals the VAT owed for the current quarter to date plus any return filed and not yet paid. VAT returns and payments are due one calendar month and seven days after the end of the VAT period (GOV.UK). Check that invoices without VAT, such as from suppliers who are not registered, have been coded correctly. Moving the VAT element into a separate account as it is collected is covered in setting aside money for VAT, PAYE and Corporation Tax.
Stock and work in progress
If you hold stock, count it or take the figure from your stock system, value it at cost, and post the movement from last month. If you work on jobs, add up the costs on jobs started and not yet invoiced, and post the change in work in progress. Without this step, a month in which you bought heavily for next month's jobs shows a loss it did not make. The guide to job costing covers valuing work in progress.
Fixed assets and depreciation
Post any equipment, vehicles or computers bought in the month to the fixed asset register at cost, along with anything sold or scrapped. Then post the month's depreciation. A £30,000 van written off in equal amounts over five years is £6,000 a year, or £500 a month. Agree the register's total to the balance sheet.
Review
On the fifth day, read the profit and loss account and the balance sheet together before anyone else sees them.
- Each profit and loss line compared with last month and the budget, and any large movement explained
- Gross margin within its usual range
- Every balance sheet account reconciled or explained
- Director's loan account agreed
- The month locked in Xero so nothing can be posted to it later
A five-day timetable
Pin a timetable to the wall and work through it in the same order every month, counting working days from the first day after the month end.
- Day 1: every bank, card, loan and payment account reconciled to its statement balance.
- Day 2: all sales invoiced, all supplier bills received and posted, aged debtors and creditors reviewed.
- Day 3: accruals, prepayments and the payroll journal posted, and PAYE and pension control accounts agreed.
- Day 4: VAT control account reconciled, stock and work in progress counted and posted, fixed assets and depreciation posted.
- Day 5: profit and loss and balance sheet reviewed, corrections posted and the month locked.
Give each step a named owner, and record the date it was finished. If a step slips, the record shows which one, and it can be moved earlier or split up the following month.
Keeping the close to five days
The close is quicker when most of the work is done during the month.
- Reconcile the bank every week, so day 1 only covers the last few days of the month.
- Collect receipts as they happen, with a receipts app or a photo sent from the phone on the day.
- Send supplier bills to one email address that posts them into Xero, so none sit in someone's inbox.
- Set up repeating journals for depreciation and for prepayments spread over the year, so they post themselves each month.
- Agree a cut-off with staff: sales invoiced and expenses claimed by the last working day, or they go into next month.
- Keep a list of accruals that come up each month, such as energy and telephone, and check it each time.
What management accounts need from the close
The management accounts are built from the closed month: the profit and loss against the budget, the balance sheet, cash against the forecast, aged debtors and creditors, and your KPIs. A monthly board pack adds commentary on the variances and the actions agreed. Both depend on the close being finished on time, every month, so the figures are ready while there is still time to act on them.
The Buzz finance team
Finance Manager closes your month within a few working days, with weekly bookkeeping in Xero, payroll and VAT returns, for £750 + VAT a month. Financial Controller, at £1,500 + VAT a month, adds the monthly board pack, invoicing and chasing customers, supplier payment runs and cash alerts.
Full Payment Submission deadline: GOV.UK, Running payroll, reporting to HMRC. VAT return and payment deadline: GOV.UK, Submit a VAT Return.
Questions
What is a month-end close?
A month-end close is the set of checks and adjustments made after each month ends, so the accounts for that month are complete and correct. It covers reconciling the bank, checking the sales and purchase ledgers, posting accruals, prepayments, payroll and depreciation, reconciling VAT and stock, and reviewing the profit and loss account and balance sheet. The closed figures are then used for the management accounts. Work through it in the same order every month: day 1 the bank, day 2 the sales and purchase ledgers, day 3 accruals, prepayments and payroll, day 4 VAT, stock and fixed assets, and day 5 the review and the lock. Give each step a named owner. The management accounts are built from the closed month.
How long should a month-end close take?
A small business can close its month within five working days of the month end. That leaves time for the management accounts to be produced and reviewed in the second week of the following month. The close is quicker when the bank is reconciled each week during the month and supplier bills and receipts are posted as they arrive. In a five-day timetable, every bank and card account is reconciled on day 1, sales are invoiced and supplier bills posted on day 2, accruals, prepayments and the payroll journal go in on day 3, VAT, stock and depreciation on day 4, and the review and lock on day 5. Repeating journals for depreciation and prepayments, and one email address that posts supplier bills into Xero, also save time.
What is the difference between an accrual and a prepayment?
An accrual adds a cost that belongs to the month but has not yet been billed, and a prepayment takes out the part of a bill paid this month that belongs to later months. Electricity used but not yet invoiced is an accrual. An annual insurance premium paid in one month is a prepayment, released as a cost of one twelfth each month. Both reverse at the start of the next month. In the example month, £1,200 of electricity used but not yet billed comes off profit, and £5,500 of a £6,000 annual insurance premium is carried forward to the next eleven months. Posted as a single cost, the insurance would make the month it was paid look poor and the following eleven look better than they were. Keep a list of the accruals that come up each month and check it at every close.
Why lock the month in Xero after the close?
Locking the month stops anyone posting or changing transactions dated in it, so the figures in the management accounts stay the same as the figures in the books. Without a lock date, a late bill or a corrected entry can change a month that has already been reported. Corrections found later are then posted in the current month with a note. Lock the month on day 5, after the profit and loss account and balance sheet have been reviewed and every balance sheet account reconciled or explained. Directors reading a monthly board pack, and any lender that receives your management accounts, then see the same figures each time they look. Make the lock a step in the close timetable with a named owner.
Sample monthly board pack
Six pages for one month at an invented catering wholesaler with 18 staff, prepared the way the finance team prepares one for a client.
- 1Summary
- 2Profit and loss
- 3Balance sheet
- 4Cash
- 5Customers and suppliers
- 6Commentary
More guides
What does a part-time finance director do?
What a part-time or fractional finance director does, the first three months, how it differs from a financial controller, and what one costs.
Finance manager or financial controller?
What a finance manager does, what a financial controller adds, the month-end close, deadlines, how to choose, and what each costs to employ or outsource.
In-house or outsourced bookkeeper?
What employing a bookkeeper costs once National Insurance, pension and holiday cover are added, what an outsourced service covers, and how to switch.
How to run a monthly board meeting
Who attends a board meeting in an owner-managed company, what goes in the board pack, a standard agenda, the decisions and actions log, and the minutes.
Replacing a bookkeeper who has left
Keeping payroll, VAT and the books running when your bookkeeper goes.
The cost of employing a financial controller
What a finance manager, financial controller and finance director cost to employ in 2026 to 2027, with National Insurance and pension, against Buzz fees.
How much a part-time finance director costs
A part-time finance director from Buzz costs £2,000 + VAT a month with the finance team included, against £128,508.40 a year to employ one.
Fractional CFO, part-time FD or interim FD
What a fractional CFO, a part-time finance director, an outsourced CFO and an interim FD each are, and how to choose one for your business.
The 13-week cash flow forecast
How to build a 13-week cash flow forecast, update it every Monday and act on it, with payroll, PAYE, VAT and Corporation Tax in the right weeks.
Month-end close for a small business
How to close the books by working day 10: the reconciliations, accruals and prepayments, the review, and what the management accounts should show.
Debtor control and getting paid faster
Payment terms, invoicing, a chase sequence by day, debtor days, and statutory late payment interest and compensation at the rates on GOV.UK today.
The monthly KPI pack and board pack
The 8 to 12 numbers an owner-managed business should see every month, how to read them, and what a monthly board pack contains, with a worked example.
13-week cash flow forecast template
A free Excel template for the next 13 weeks of receipts, payments and bank balance.
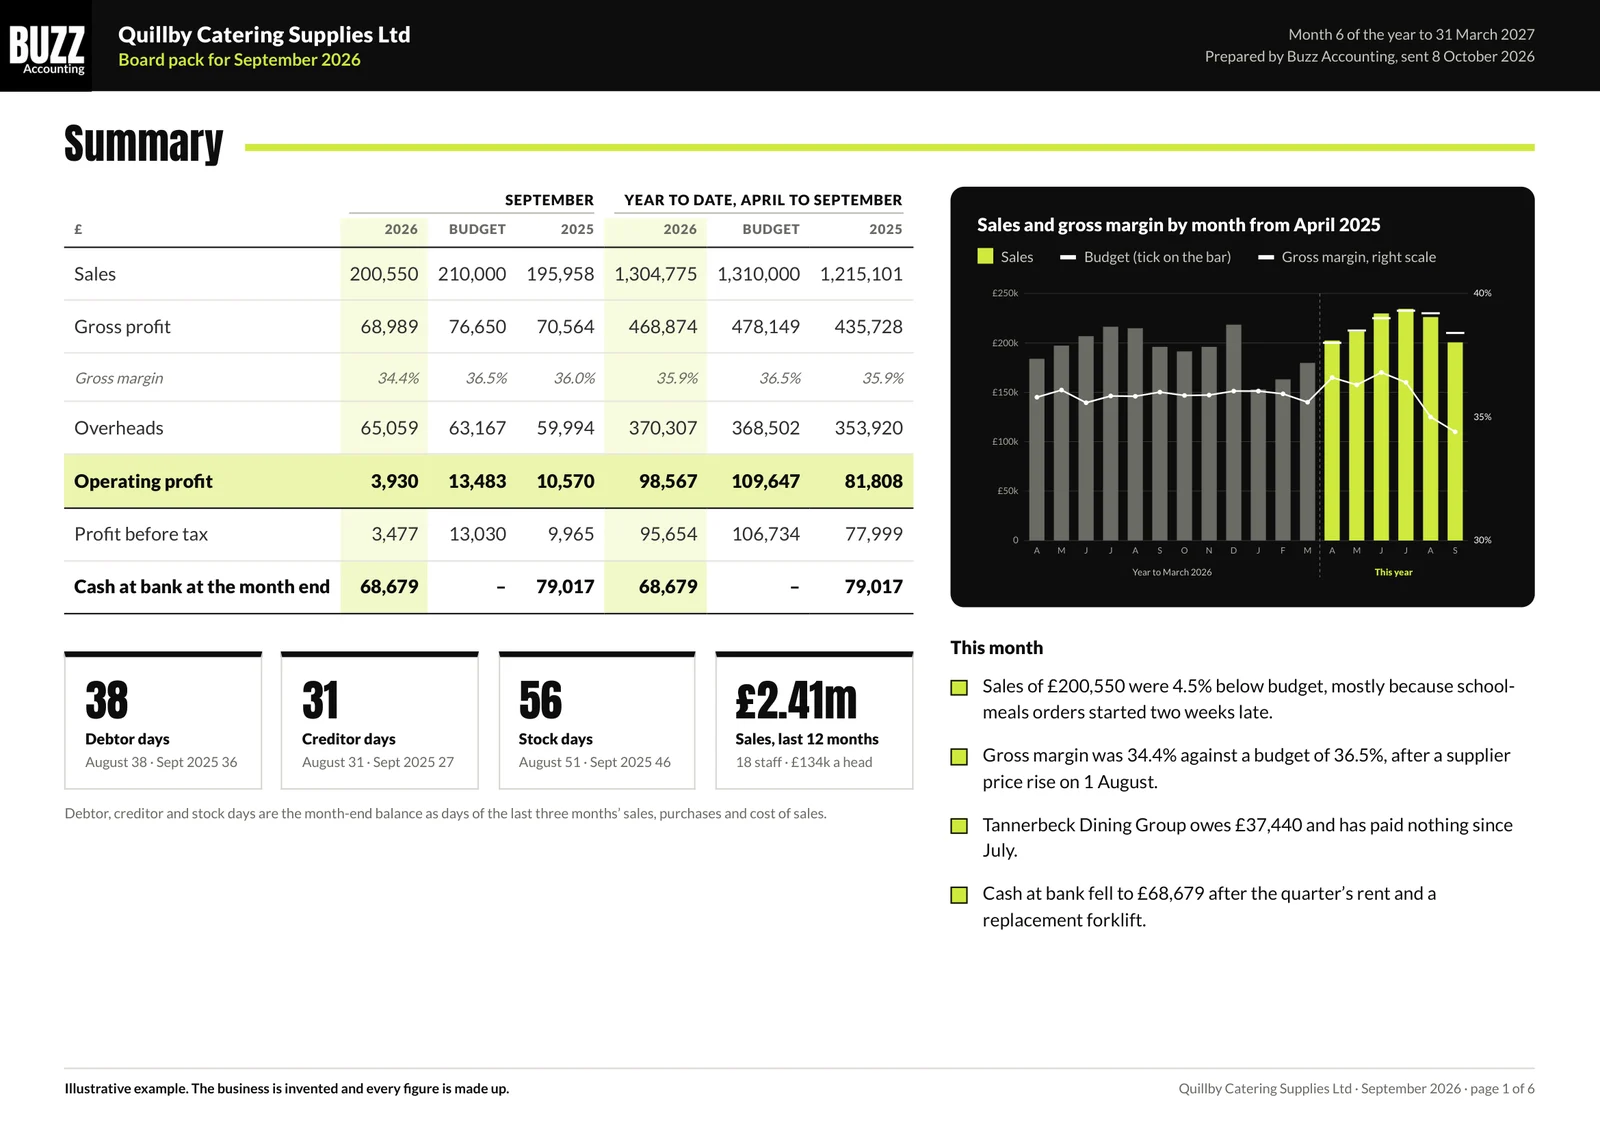
Sample board pack
A six-page monthly board pack to download.
Cash flow forecasting
How to build a 12-month forecast and keep it up to date.
How to read a cash flow forecast
What each line means and where a tight month shows up.
Why a profitable business runs out of cash
Profit is counted when you invoice and cash moves when you are paid. Where the difference goes, how much cash you need, and ways to release it.
How to reduce debtor days
How to work out debtor days, the steps that bring them down, from payment terms to a weekly chasing routine, and the cash a lower figure releases.
Charging interest on late payments
Statutory interest at 8% above base rate, the fixed sums of £40, £70 and £100, when the late payment law applies, how to claim and how to word your terms.
Setting aside money for VAT, PAYE and Corporation Tax
When VAT, PAYE and Corporation Tax are due, how to work out what to move to a tax account each month, and a worked example for a limited company.
CIS deductions and a builder's cash flow
How CIS deductions of 20%, 30% or nothing reduce what a subcontractor banks on each invoice, HMRC deadlines, and gross payment status.
Outsourced credit control and how it works
What an outsourced credit controller does each week, how it runs in your Xero, what it costs against employing one, and the cash it releases.
Cash flow forecasting in Xero
What Xero's short-term cash flow projection shows, what it leaves out, and how to keep a 13-week or 12-month forecast alongside Xero.
Management accounts explained
The contents of a monthly management pack, and how to read it.
KPIs to check every month in a small business
The KPIs an owner-managed business checks each month, how to set targets, leading and lagging measures, and a worked monthly KPI sheet.
Sample board pack
A six-page monthly board pack to download.
Gross margin explained
What gross margin is, how it differs from mark-up, how to calculate it, what moves it and why to check it monthly, with a worked example of the confusion.
Working capital explained
What working capital is, how to calculate it from a balance sheet, the working capital cycle in days, why growth uses cash, and a worked example.
Budget against actual variances explained
How to compare each month's results with the budget, tell favourable from adverse variances, split price from volume and decide which ones to act on.
What management accounts cost and include
Management accounts from £375 a month quarterly or £499 monthly + VAT: what a monthly set contains, what the owner provides and when it should arrive.
Management accounts for a construction company
Management accounts for builders and contractors: work in progress, retentions, CIS deductions, the VAT reverse charge and margin by contract.
Setting up monthly management reports in Xero
How to set up monthly management reports in Xero: the ledger work first, then the Management Report pack, budget variance, tracking and commentary.
How to price for profit
What a price change does to profit, worked through.
Turnover up, profit down
Why sales can rise while profit falls, and where to look.
How to set an annual budget for your business
Six steps to next year's budget, a month-by-month worked example, seasonality, wage rises from April 2026, and reforecasting during the year.
Break-even point explained
How to work out break-even in sales and in units from fixed costs, variable costs and contribution margin, with a worked example and the margin of safety.
What a price rise does to profit
How a small price rise flows straight to profit, how many customers you could lose and still be better off, and how much more you must sell after a discount.
Job costing for small businesses
How to cost each job with materials, labour at a loaded hourly rate, subcontractors and overheads, compare quoted with actual, and value work in progress.
What a bank wants to see in a business plan
What a lender reads in a business plan: the amount and purpose, ability to repay, forecasts, assumptions, security, guarantees and the people running it.
Talk to us
Tell us about the business and what is taking up your week, or book 30 minutes with Peter. He will come back within 48 hours with the level that fits and a fixed monthly fee.
Book a callOr call
07476 989568Accreditations and partners