Debtor days is the average number of days your customers take to pay you: the amount they owe you today, divided by your annual sales, multiplied by 365. You bring it down by agreeing clear payment terms, invoicing on the day the work is done, taking deposits and stage payments, and chasing every overdue invoice on a fixed weekly routine. Each day you take off the figure moves a day of sales from your customers' bank accounts into yours.
How to work out debtor days
Take the total your customers owe you from the aged debtors report in Xero or your accounting software. Divide it by your sales for the last 12 months and multiply by 365. If your sales are seasonal, use the last three months of sales multiplied by four, so the figure reflects the invoices customers owe you now.
Keep VAT consistent on both sides. The debtors figure includes VAT because customers owe you the full invoice, while the sales figure in your profit and loss account leaves it out. Either add VAT to the sales figure or take it off the debtors figure before you divide.
Compare the answer with your payment terms. With 30-day terms and debtor days of 52, customers are paying three weeks late on average. Work the figure out on the same day each month and put it next to the bank balance in your management accounts, so a rise shows up within a month. The debtor days calculator does the arithmetic and shows the cash tied up at your current figure.
Payment terms agreed before the work starts
Set your terms in writing before you start a job or deliver an order: the number of days, the date they run from, how the customer pays and what happens when payment is late. Put the same terms on the quote, the order confirmation and every invoice, and ask a new customer to sign or accept them online.
When no payment date has been agreed between two businesses, GOV.UK says a payment is late 30 days after the later of the customer receiving the invoice and you delivering the goods or service. Payment periods agreed between businesses must usually be no longer than 60 days, and a longer period has to be fair to both sides. Shorter terms for new customers, and for any customer who has paid late before, are yours to set.
Your terms can also say you will charge interest and compensation under the late payment law. The guide on charging interest on late payments sets out the rate, the fixed sums and the wording.
Invoicing on the day the work is done
The customer's payment period starts when they have the invoice, so every day between finishing the work and sending the invoice adds a day to debtor days. A business that invoices once a month in a batch makes the customer whose job finished on the 3rd wait four weeks for a bill, and then gives them 30 days on top.
Send each invoice the day the work is finished or the goods leave, and check it before it goes:
- The customer's purchase order number, if they use one, and the name of the person who ordered the work
- The correct legal name and address of the customer, matching their records
- A description the customer's accounts team can match to the order without asking
- The due date written as a date, and your bank details
- A payment link so the customer can pay by card or bank transfer from the invoice
An invoice with a missing purchase order number or the wrong address is often set aside by the customer's accounts team until someone corrects it. Ask each large customer how they pay suppliers: which day their payment run happens, who approves invoices and whether you need to upload them to a supplier portal. An invoice that arrives the day after a monthly payment run waits a month.
Deposits and stage payments
For any job that runs over several weeks, agree a payment schedule before you start: a deposit with the order, payments at agreed stages and the balance on completion. On a £40,000 fit-out lasting eight weeks, a 25% deposit, 50% at the halfway point and 25% on completion means £10,000 arrives before you buy the materials, and the largest payment lands while the job is still running.
Recurring services can be billed in advance at the start of each month. Annual contracts can be billed quarterly or monthly in advance. Each of these moves cash in before you pay for the work.
A weekly chasing routine
Chasing works when it happens every week, on the same day, by the same person, whatever else is going on. A routine for 30-day terms might run like this:
- Five days before the due date, an email with a copy of the invoice and the date it falls due
- On the due date, a short email asking the customer to confirm payment is on its way
- Seven days overdue, a phone call to the person who approves payment, with a note of the date they give
- Fourteen days overdue, a second call and a written reminder of your terms, including interest
- Thirty days overdue, a final letter with a date for payment, and any further work held until it is paid
Keep a note against each invoice of every call, the name of the person you spoke to and the date they promised. Call again on the day after a promised date if the money has not arrived. Start each week's chasing from the aged debtors report, oldest and largest invoices first.
Direct debit, card payments and monthly statements
For fixed amounts that recur, such as monthly service fees, collect by direct debit. The customer signs a mandate once, and you collect on the due date each month without waiting for them to make the payment. For one-off invoices, a card or bank payment link on the invoice lets the customer pay in a minute.
A statement at the start of each month lists every open invoice, its date and its amount. It helps the customer's accounts team match what they owe, and it shows up any invoice they say they never received while there is still time to resend it.
The cash released by lower debtor days
Each day you take off debtor days releases one day's sales. A business with £1.2 million of annual sales bills about £3,288 a day.
Cash released by bringing debtor days from 70 to 45
| Annual sales | £1,200,000 |
| Sales a day (£1,200,000 divided by 365) | £3,288 |
| Owed by customers today | £230,000 |
| Debtor days today | 70 |
| Owed by customers at 45 days | £147,945 |
| Cash released | £82,055 |
An example on invented round numbers, with VAT left out of both figures.
The £82,055 arrives once, as customers pay faster, and stays in the bank for as long as debtor days stay at 45. It can clear an overdraft, pay a supplier early for a discount or fund growth without a loan. The guide on working capital shows how debtor days fit with stock and supplier terms.
Credit control from Buzz
The Buzz financial controller service invoices your customers promptly and chases them every week, alongside a monthly board pack, supplier payment runs and a cash alert when the bank balance falls below a level you set. It costs £1,500 + VAT a month. The credit control page sets out the chasing work in detail.
Questions
What is a good debtor days figure?
A good debtor days figure is one close to your own payment terms. With 30-day terms, debtor days of 30 to 35 mean customers are paying on time or close to it, and anything well above that is cash sitting with your customers. Compare the figure with your terms each month and with the same month last year, because a rising trend matters more than any single reading. The debtor days calculator shows the cash tied up at your current figure. Each day above your terms holds back a day of sales. A business with £1.2 million of annual sales bills about £3,288 a day, so bringing debtor days from 70 to 45 releases £82,055. Invoicing on the day the work is done and chasing on a fixed weekly routine are the two steps that bring the figure down.
How do you calculate debtor days?
Divide the amount customers owe you by your annual sales and multiply by 365. If customers owe you £100,000 and your sales for the year are £600,000, debtor days are 61. Use the aged debtors total from your accounting software on the day you work it out, and keep VAT consistent by either adding it to the sales figure or taking it off the debtors figure before you divide. If your sales are seasonal, use the last three months of sales multiplied by four, so the figure reflects the invoices customers owe you now. Compare the answer with your payment terms: with 30-day terms, debtor days of 52 mean customers are paying three weeks late on average. The debtor days calculator does the arithmetic.
Can I charge interest on late invoices?
Yes, when both you and your customer are businesses, you can charge statutory interest at 8% a year above the Bank of England base rate, plus a fixed sum of £40, £70 or £100 depending on the size of the debt (GOV.UK). If your contract sets its own interest rate, that rate applies in place of statutory interest. Send a new invoice when you add interest to the amount owed. On a £12,000 invoice paid 40 days late with a reference rate of 4%, the statutory rate is 12%, the interest comes to £157.81 and the fixed sum is £100, so the claim is £257.81. The guide on charging interest on late payments sets out the wording for your terms.
Who should chase unpaid invoices in a small business?
One named person should chase unpaid invoices every week, on the same day, working from the aged debtors report. That can be a bookkeeper, an office manager, a financial controller or the owner, provided the routine is written down and followed whatever else is happening that week. The person chasing needs authority to hold further work for a customer who is well overdue, and a note of every promise made. Chase on a set timetable: an email five days before the due date, another on the due date, a phone call at seven days overdue, a second call and a written reminder of your terms at 14 days, and a final letter at 30 days. The credit control work is part of the Buzz Financial Controller service at £1,500 + VAT a month.
Sample monthly board pack
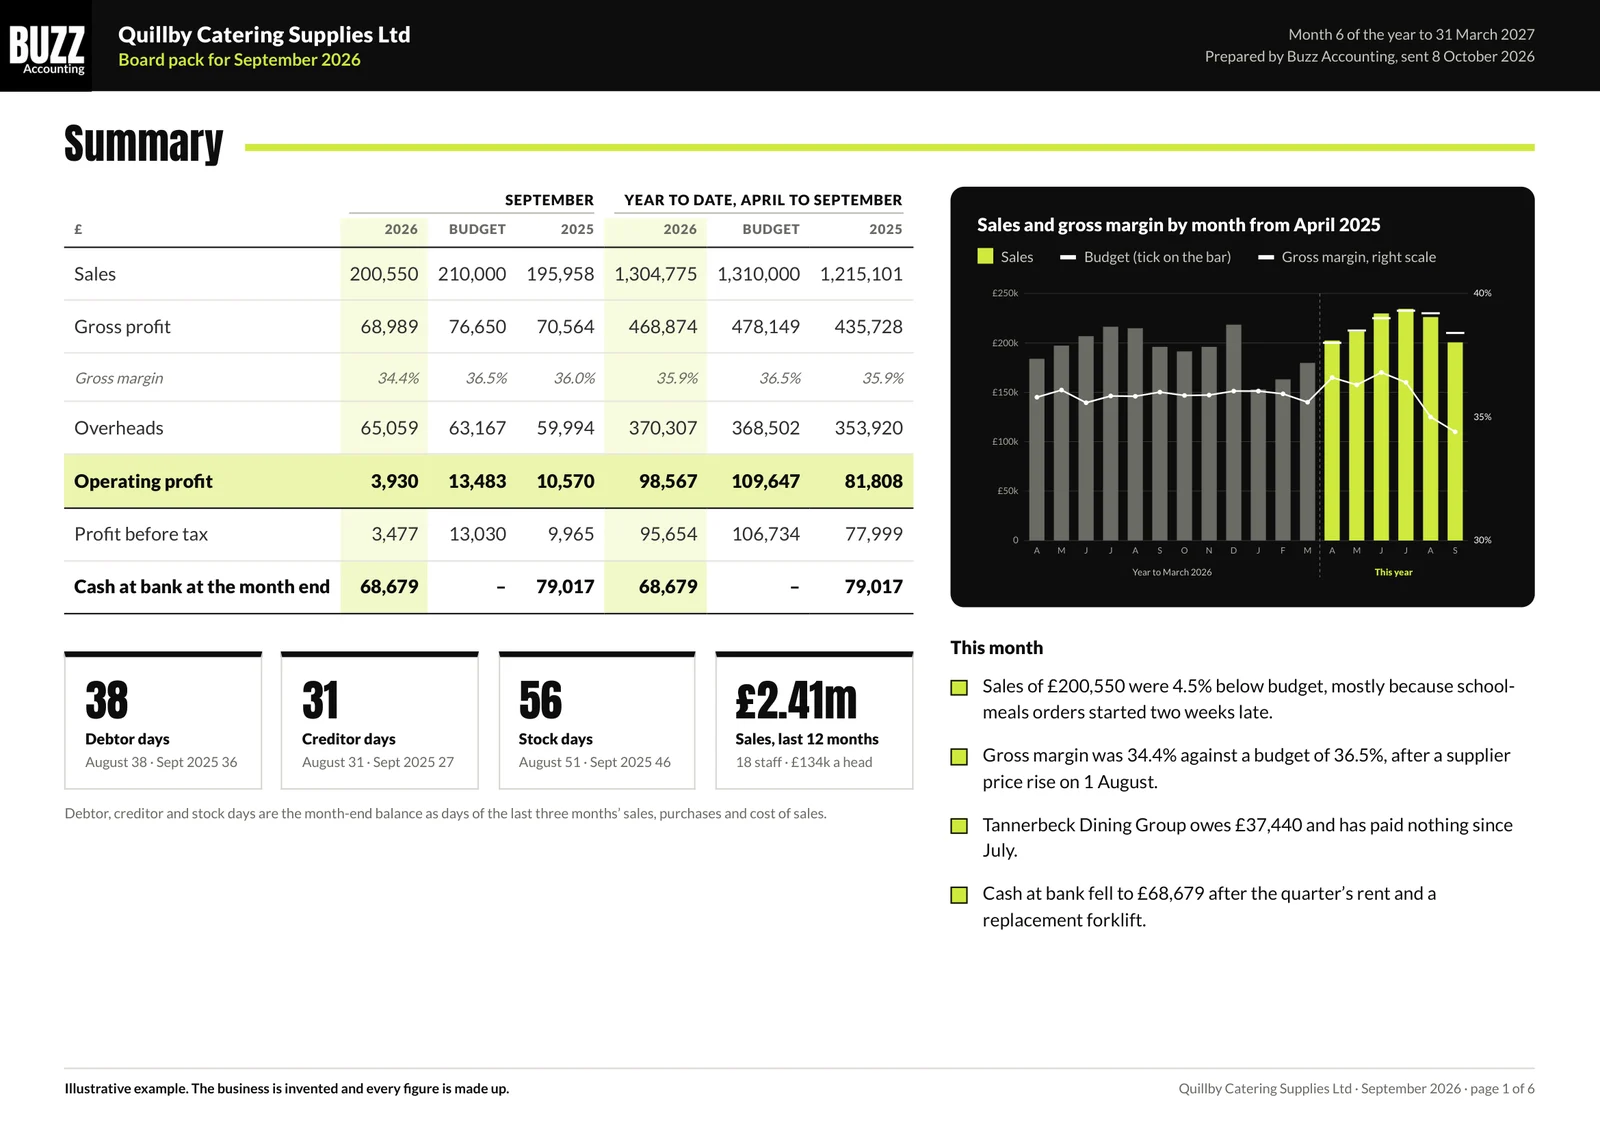
Six pages for one month at an invented catering wholesaler with 18 staff, prepared the way the finance team prepares one for a client.
- 1Summary
- 2Profit and loss
- 3Balance sheet
- 4Cash
- 5Customers and suppliers
- 6Commentary
More guides
Cash flow forecasting
How to build a 12-month forecast and keep it up to date.
How to read a cash flow forecast
What each line means and where a tight month shows up.
Why a profitable business runs out of cash
Profit is counted when you invoice and cash moves when you are paid. Where the difference goes, how much cash you need, and ways to release it.
Charging interest on late payments
Statutory interest at 8% above base rate, the fixed sums of £40, £70 and £100, when the late payment law applies, how to claim and how to word your terms.
Setting aside money for VAT, PAYE and Corporation Tax
When VAT, PAYE and Corporation Tax are due, how to work out what to move to a tax account each month, and a worked example for a limited company.
CIS deductions and a builder's cash flow
How CIS deductions of 20%, 30% or nothing reduce what a subcontractor banks on each invoice, HMRC deadlines, and gross payment status.
Outsourced credit control and how it works
What an outsourced credit controller does each week, how it runs in your Xero, what it costs against employing one, and the cash it releases.
Cash flow forecasting in Xero
What Xero's short-term cash flow projection shows, what it leaves out, and how to keep a 13-week or 12-month forecast alongside Xero.
The 13-week cash flow forecast
How to build a 13-week cash flow forecast, update it every Monday and act on it, with payroll, PAYE, VAT and Corporation Tax in the right weeks.
Month-end close for a small business
How to close the books by working day 10: the reconciliations, accruals and prepayments, the review, and what the management accounts should show.
Debtor control and getting paid faster
Payment terms, invoicing, a chase sequence by day, debtor days, and statutory late payment interest and compensation at the rates on GOV.UK today.
The monthly KPI pack and board pack
The 8 to 12 numbers an owner-managed business should see every month, how to read them, and what a monthly board pack contains, with a worked example.
13-week cash flow forecast template
A free Excel template for the next 13 weeks of receipts, payments and bank balance.
Sample board pack
A six-page monthly board pack to download.
Management accounts explained
The contents of a monthly management pack, and how to read it.
KPIs to check every month in a small business
The KPIs an owner-managed business checks each month, how to set targets, leading and lagging measures, and a worked monthly KPI sheet.
Sample board pack
A six-page monthly board pack to download.
Gross margin explained
What gross margin is, how it differs from mark-up, how to calculate it, what moves it and why to check it monthly, with a worked example of the confusion.
Working capital explained
What working capital is, how to calculate it from a balance sheet, the working capital cycle in days, why growth uses cash, and a worked example.
Budget against actual variances explained
How to compare each month's results with the budget, tell favourable from adverse variances, split price from volume and decide which ones to act on.
What management accounts cost and include
Management accounts from £375 a month quarterly or £499 monthly + VAT: what a monthly set contains, what the owner provides and when it should arrive.
Management accounts for a construction company
Management accounts for builders and contractors: work in progress, retentions, CIS deductions, the VAT reverse charge and margin by contract.
Setting up monthly management reports in Xero
How to set up monthly management reports in Xero: the ledger work first, then the Management Report pack, budget variance, tracking and commentary.
How to price for profit
What a price change does to profit, worked through.
Turnover up, profit down
Why sales can rise while profit falls, and where to look.
How to set an annual budget for your business
Six steps to next year's budget, a month-by-month worked example, seasonality, wage rises from April 2026, and reforecasting during the year.
Break-even point explained
How to work out break-even in sales and in units from fixed costs, variable costs and contribution margin, with a worked example and the margin of safety.
What a price rise does to profit
How a small price rise flows straight to profit, how many customers you could lose and still be better off, and how much more you must sell after a discount.
Job costing for small businesses
How to cost each job with materials, labour at a loaded hourly rate, subcontractors and overheads, compare quoted with actual, and value work in progress.
What does a part-time finance director do?
What a part-time or fractional finance director does, the first three months, how it differs from a financial controller, and what one costs.
Finance manager or financial controller?
What a finance manager does, what a financial controller adds, the month-end close, deadlines, how to choose, and what each costs to employ or outsource.
Month-end close checklist
The steps to close the books within five working days: bank, ledgers, accruals, prepayments, payroll, VAT, stock, fixed assets and a final review.
In-house or outsourced bookkeeper?
What employing a bookkeeper costs once National Insurance, pension and holiday cover are added, what an outsourced service covers, and how to switch.
How to run a monthly board meeting
Who attends a board meeting in an owner-managed company, what goes in the board pack, a standard agenda, the decisions and actions log, and the minutes.
Replacing a bookkeeper who has left
Keeping payroll, VAT and the books running when your bookkeeper goes.
The cost of employing a financial controller
What a finance manager, financial controller and finance director cost to employ in 2026 to 2027, with National Insurance and pension, against Buzz fees.
How much a part-time finance director costs
A part-time finance director from Buzz costs £2,000 + VAT a month with the finance team included, against £128,508.40 a year to employ one.
Fractional CFO, part-time FD or interim FD
What a fractional CFO, a part-time finance director, an outsourced CFO and an interim FD each are, and how to choose one for your business.
What a bank wants to see in a business plan
What a lender reads in a business plan: the amount and purpose, ability to repay, forecasts, assumptions, security, guarantees and the people running it.
Talk to us
Tell us about the business and what is taking up your week, or book 30 minutes with Peter. He will come back within 48 hours with the level that fits and a fixed monthly fee.
Book a callOr call
07476 989568Accreditations and partners